The 2020s have been a rollercoaster for the global economy, but one phenomenon stands out to me as particularly fascinating: the K-shaped housing market. It’s a term that’s been thrown around, but what does it really mean? And more importantly, why does it matter? Let’s dive in.
The Economic Rollercoaster: A Quick Recap
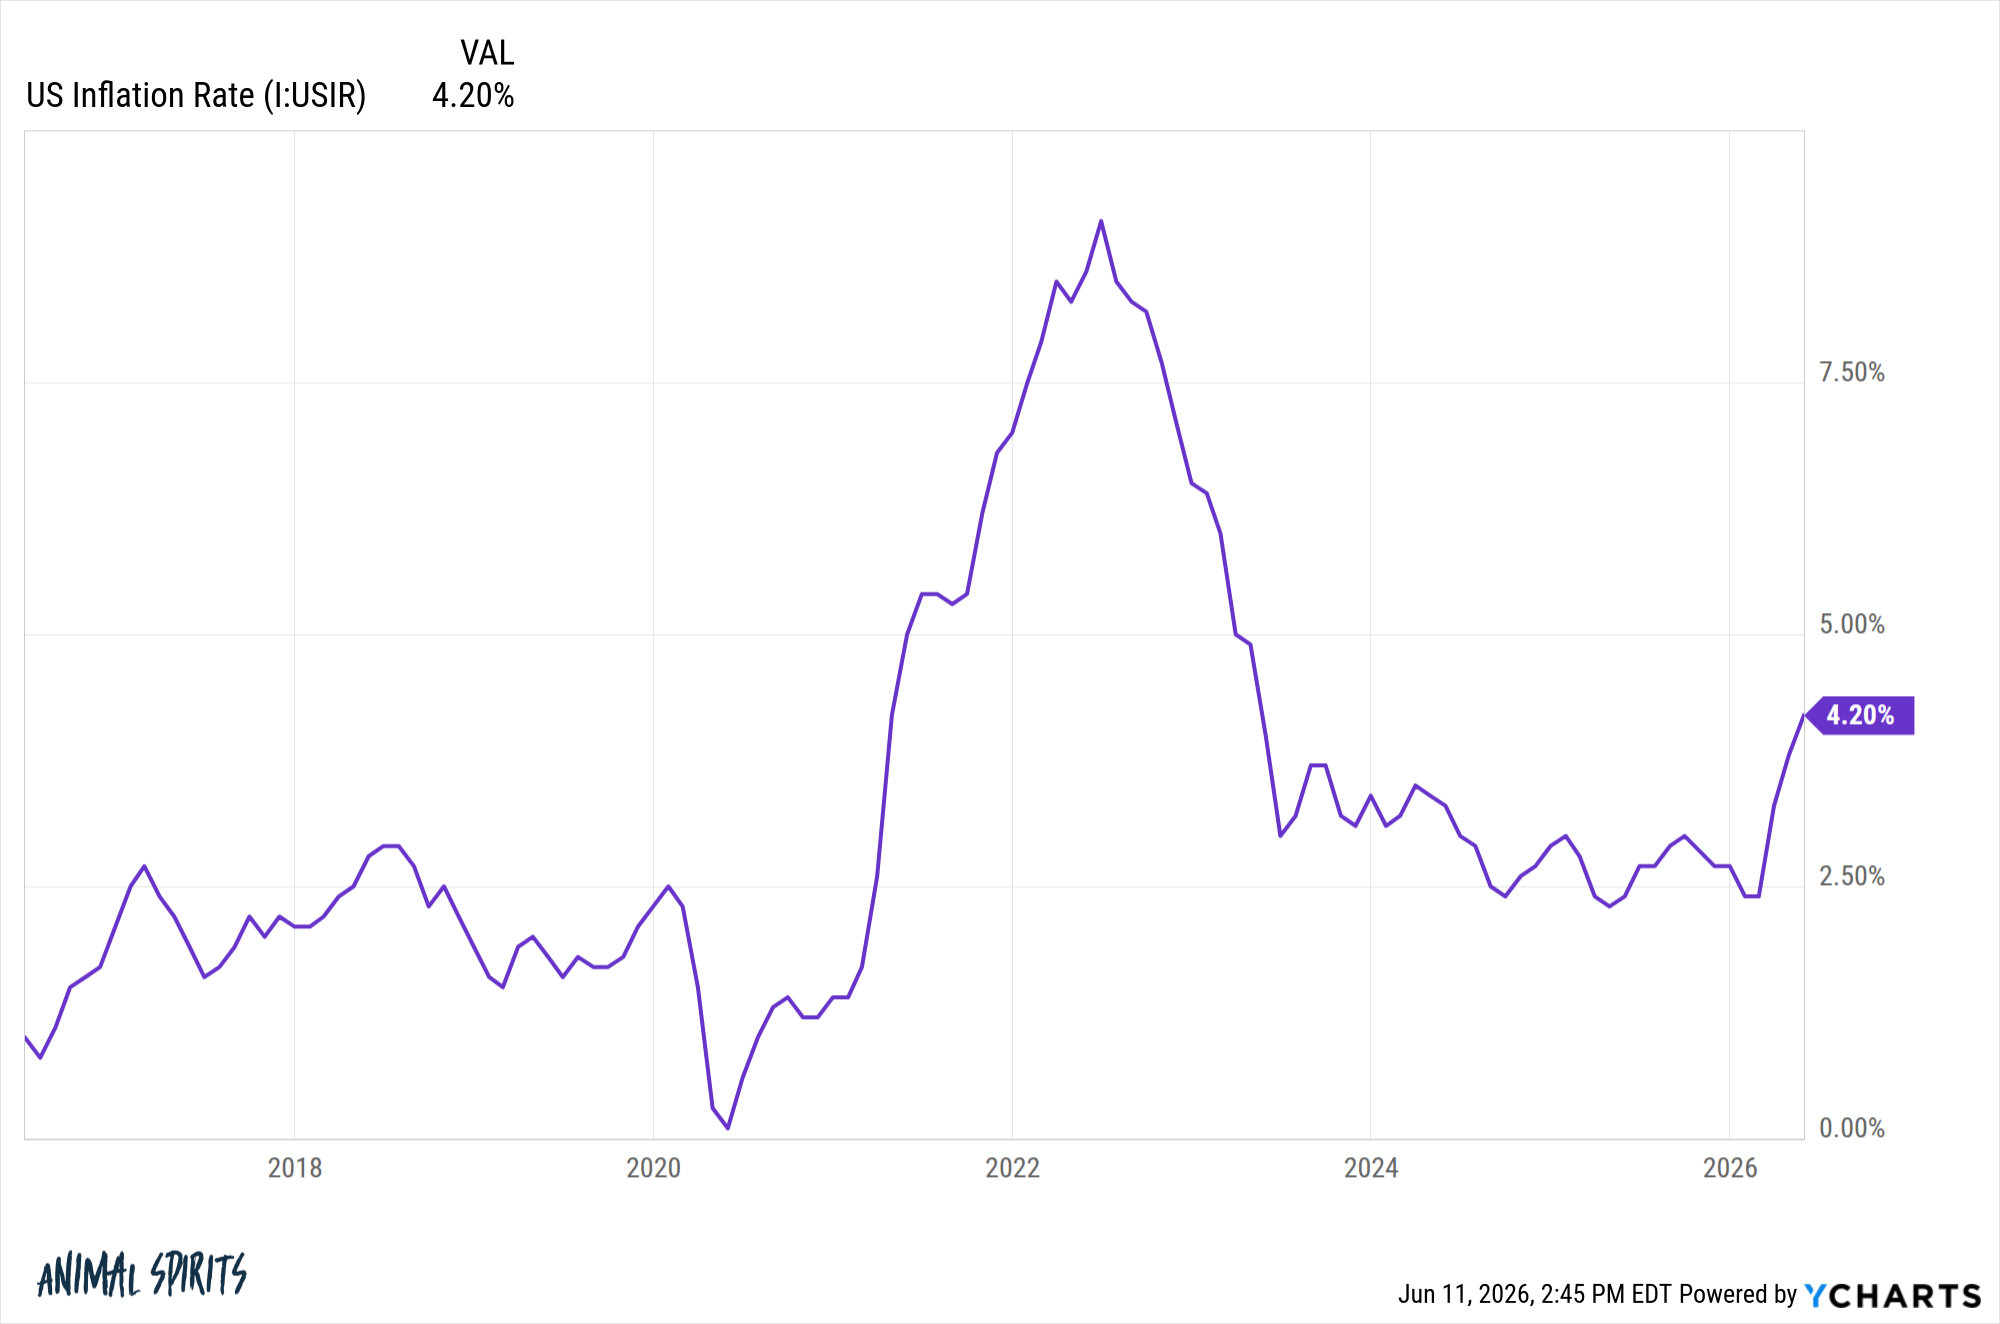
First, let’s set the stage. The pandemic disrupted supply chains, inflation hit 40-year highs, and geopolitical tensions like the Russia-Ukraine war and Iran conflict sent gas prices soaring. Yet, despite these headwinds, consumers kept spending. How? One word: housing. Or rather, the timing of it.
What makes this particularly fascinating is how a single decision—buying a home before 2022—has created a stark divide. Those who locked in low mortgage rates (think 3%) essentially secured a financial fortress against inflation. Today, with inflation above 4%, they’re borrowing at negative real rates. It’s like the universe handed them a 'get out of jail free' card.
The Lucky Few vs. the Rest
Here’s where the K-shape emerges. On one side, you have homeowners who bought before 2022, enjoying historically low mortgage payments. On the other, you have everyone else—first-time buyers, renters, and those who missed the boat. For them, housing is now a luxury, not a given. Mortgage rates have doubled, and home prices are up 30% since 2020. It’s a tale of two economies, and housing is the dividing line.
In my opinion, this isn’t just about housing affordability. It’s about economic resilience. Those with low mortgage payments have disposable income to spend elsewhere, fueling retail sales and stock market investments. Meanwhile, the unlucky majority are stretched thin, struggling to enter the market. This disparity isn’t just a housing issue—it’s a wealth gap in disguise.
The Inflation Hedge of a Lifetime
Let’s pause and appreciate the scale of this hedge. A 3% mortgage in a 4%+ inflation environment is essentially free money. It’s no wonder consumer spending has remained robust. But here’s the kicker: this advantage isn’t going away anytime soon. Over 40% of homeowners own their homes outright, and half of borrowers have rates below 4%. That’s a lot of people with financial breathing room.
What many people don’t realize is how this dynamic has skewed economic forecasts. Analysts expected a recession, but households with low housing costs kept the economy afloat. It’s a reminder that timing and luck—not just policy—drive economic outcomes. If you take a step back and think about it, this isn’t just about housing; it’s about the role of chance in financial success.
The Broader Implications: A Wealth Gap in Disguise
The K-shaped housing market isn’t just a real estate story—it’s a societal one. It highlights how systemic factors like interest rates and inflation can create winners and losers. Those who bought homes in the 2010s or early 2020s are now sitting on a financial advantage that others may never catch up to. This raises a deeper question: Is homeownership becoming a privilege rather than a milestone?
From my perspective, this trend could exacerbate inequality. Wealthier households are more likely to have benefited from low rates, while younger or lower-income buyers are priced out. It’s a cycle that perpetuates itself, with long-term implications for social mobility. If housing remains unaffordable, we’re not just talking about a market correction—we’re talking about a generational divide.
What’s Next? The Uncertain Future of Housing
The big question is: How long will this dynamic last? Mike Simonsen suggests it could persist for years, but history tells us housing markets are unpredictable. The 2000s bubble, the 2010s affordability boom, and the pandemic-driven surge all show how quickly things can shift. An external shock—another recession, a policy change, or even a shift in remote work trends—could upend the current balance.
One thing that immediately stands out is how fragile this equilibrium is. The housing market has always been a game of timing and luck, but the stakes have never been higher. For those locked out, the question isn’t just about affording a home—it’s about affording a future.
Final Thoughts: A System in Need of Rethinking
As I reflect on the K-shaped housing market, I’m struck by how much it reveals about our economic system. It’s not just about supply and demand; it’s about who gets to participate in wealth creation. Personally, I think we need a broader conversation about housing policy, affordability, and the role of luck in financial success.
What this really suggests is that the housing market isn’t just a market—it’s a mirror. It reflects our priorities, our inequalities, and our opportunities. Until we address the root causes of this divide, the K-shape will persist, shaping not just our economy, but our society. And that’s a thought worth pondering.